BLOG
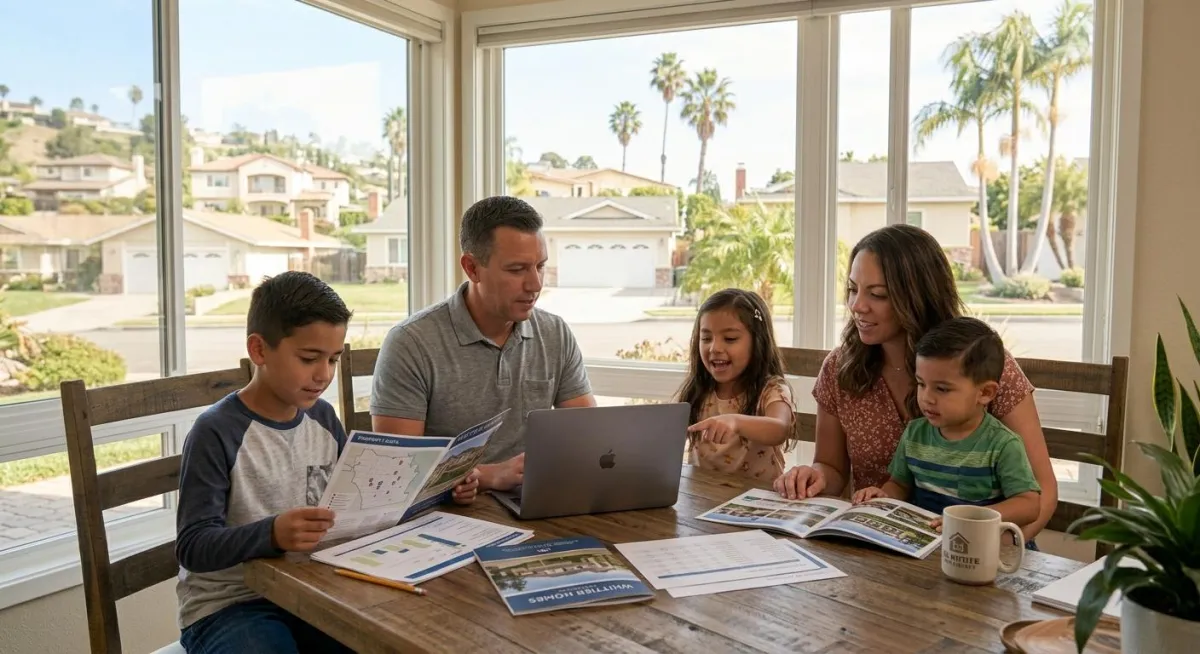
Should You Buy a Bigger Home in Whittier Before Interest Rates Drop?
Should You Buy a Bigger Home in Whittier Before Interest Rates Drop?
One of the biggest questions Whittier move-up buyers are asking right now is:
“Should we wait for interest rates to drop before buying a bigger home?”
It is a completely understandable question.
A lot of homeowners purchased or refinanced during historically low rate periods and now feel caught between their comfortable existing payment, their growing space needs, and the higher rates available today. The idea of voluntarily increasing your monthly payment feels uncomfortable – even when the house has clearly stopped working for your family.
Let’s talk honestly about what move-up buyers in Whittier should actually be thinking about.
Why So Many Families Are Hesitating Right Now
Many Whittier homeowners currently have mortgage rates that feel extremely comfortable. Comparing that existing payment to what a move-up home would cost at today’s rates can feel genuinely shocking at first.
For a lot of homeowners, the current mortgage payment represents stability, predictability, and financial breathing room. So the idea of walking away from it feels emotionally difficult even when the home itself no longer functions well for the family living in it.
This is especially true when the family has outgrown the house in ways that create daily friction – shared bedrooms, a kitchen that cannot hold everyone at once, no dedicated workspace, a backyard that does not meet what family life actually requires.
The emotional math and the practical math are pulling in different directions. And that tension is exactly where most Whittier move-up buyers are right now.
But Waiting Has Its Own Risks
This is the part many buyers overlook when they decide to wait.
Most people assume that lower rates automatically mean a better buying environment. But if rates eventually decline meaningfully, several things may happen simultaneously:
- More buyers re-enter the market
- Competition for well-priced homes increases
- Inventory tightens
- Home prices rise in response to demand
- Multiple offers become more common again on desirable properties in Whittier’s established neighborhoods
Lower rates may improve the monthly payment calculation – but they can also eliminate the negotiating leverage that currently exists in this market. The Whittier buyer who waits for lower rates may find themselves competing against five other buyers for the same property they could have purchased today with room to negotiate on price, credits, and terms.
Waiting does not guarantee an easier experience. It just changes the specific challenge you are navigating.
The Lifestyle Cost of Waiting Is Real
This is something that does not show up in any spreadsheet but matters enormously in practice.
While a Whittier family waits for rates to improve:
- Kids keep growing
- Sports equipment and school supplies keep accumulating
- The shared bedroom that was supposed to be temporary becomes more permanent
- Morning routines in too-small spaces get harder
- Daily friction compounds slowly until the house feels louder and tighter than it should
Most families do not wake up one morning and suddenly realize they need to move. The feeling builds gradually through months or years of daily stress that wears everyone down before it is consciously recognized as a housing problem.
The cost of staying in a home that no longer fits your family is real – it just does not show up on a mortgage statement.
Interest Rates Matter – But So Does Quality of Life
Sometimes buyers become so focused on optimizing the rate that they stop evaluating how their current home is actually affecting daily life.
Most Whittier move-up buyers are not searching for luxury. They are searching for better flow, more functionality, enough bedrooms that the family does not have to negotiate every morning, and a backyard that actually gets used. Those improvements can change how every single day feels – the stress level walking out the door in the morning, the ability to decompress at home in the evening, the ease of weekend life when everyone has appropriate space.
Waiting years for a perfect rate means years of living with conditions that have already been identified as not working.
Nobody Can Predict the Perfect Time
This is worth saying directly.
No one knows exactly what rates will do, what home prices will do, or what inventory will look like six months or two years from now. Trying to perfectly time all three simultaneously is extremely difficult – and the families who spend years attempting it sometimes look back and realize they waited through conditions that were actually quite workable, in search of conditions that never fully materialized.
The Refinance Option
Many Whittier buyers who are purchasing now are making the decision with the explicit understanding that they can refinance if rates improve meaningfully. This is sometimes described as “date the rate, marry the house” – meaning the rate can be changed later, but the right house in the right neighborhood for your family is a harder thing to replicate once it is gone.
Refinancing is not guaranteed and depends on future rates, your equity position, and your financial qualifications at that time. But for buyers who find a home that genuinely fits their family’s needs and expect to stay for five to ten years or more, the possibility of future refinancing changes the calculus meaningfully.
What Whittier Families Should Actually Be Asking Right Now
Instead of asking only “where will rates go?” – the more useful question is: does our current Whittier home still genuinely support the life we are trying to build?
Because the answer to that question matters just as much as the rate environment.
If the home still fits well, the payment is comfortable, and the daily friction is low – staying and waiting may make sense. There is no urgency to move when the house is working.
But if the home has clearly stopped fitting – if the daily frustration is real, the space is genuinely inadequate, and the family’s quality of life would improve significantly with a move – then the decision to wait is not neutral. It is a choice to continue living in conditions that are not working, in exchange for the possibility of a better rate at an uncertain future date.
The Honest Framework for Thinking It Through
Before deciding to wait, ask yourself honestly:
Does our current Whittier home still support our family’s routines and daily needs? Or are we staying because the familiarity feels safer than change?
Would a different home meaningfully improve our daily stress levels – not in theory, but in the actual practical ways that show up every morning and every evening?
If rates drop and we buy in two years, what will we have given up in quality of life during that period? And is that trade-off worth the potential payment improvement?
Would waiting realistically solve the problem – or would we be waiting in the same conditions, just two years older with kids who are two years further into stages where space and privacy matter more?
Those questions do not have universal answers. They have answers that are specific to your family, your home, your finances, and your goals.
FAQ
Should I wait for interest rates to drop before buying a bigger home in Whittier?
That depends on your personal finances, your family’s space needs, and how much your current home is affecting daily life. Waiting may reduce rates but can also increase competition and home prices, while the lifestyle cost of staying continues to accumulate.
Will home prices go down if rates stay high in Whittier?
No one can predict this with certainty. Whittier’s limited inventory and consistent buyer demand have historically supported values. Any meaningful price shift would depend on a combination of factors beyond rates alone.
Can buyers refinance later if they buy now?
Possibly, depending on future rates and financial qualifications at that time. Many buyers who purchase now are doing so with the explicit plan to refinance if rates improve.
Is now a bad time to move up to a bigger home in Whittier?
Not necessarily. The right answer depends on whether your current home still works for your family and whether the move-up math is viable with your equity and income. Running the real numbers with a lender – not assuming – is the most useful first step.
Ready to Find Out What the Move-Up Math Actually Looks Like for You?
You do not need to be ready to list tomorrow to have this conversation. A single meeting to look at your current equity, what the next home would cost, and what the monthly payment difference actually is – with your equity applied as a down payment – gives you real information instead of assumptions.
Schedule a time to talk about where you are and what a realistic move-up path looks like for your specific situation.
Edgar Cuevas
Whittier and Surrounding Communities | Broker & Owner
Helping buyers and sellers navigate the housing market in:
Whittier - Norwalk - La Mirada - Santa Fe Springs - Pico Rivera - El Monte - Hacienda Heights - La Puente - Valinda - West Covina
Website: xprtrealestate.com
Say hello on socials: Instagram | Facebook | TikTok
Monthly market updates: YouTube

Blogs
Should You Buy a Bigger Home in Whittier Before Interest Rates Drop?
Should You Buy a Bigger Home in Whittier Before Interest Rates Drop?
One of the biggest questions Whittier move-up buyers are asking right now is:
“Should we wait for interest rates to drop before buying a bigger home?”
It is a completely understandable question.
A lot of homeowners purchased or refinanced during historically low rate periods and now feel caught between their comfortable existing payment, their growing space needs, and the higher rates available today. The idea of voluntarily increasing your monthly payment feels uncomfortable – even when the house has clearly stopped working for your family.
Let’s talk honestly about what move-up buyers in Whittier should actually be thinking about.
Why So Many Families Are Hesitating Right Now
Many Whittier homeowners currently have mortgage rates that feel extremely comfortable. Comparing that existing payment to what a move-up home would cost at today’s rates can feel genuinely shocking at first.
For a lot of homeowners, the current mortgage payment represents stability, predictability, and financial breathing room. So the idea of walking away from it feels emotionally difficult even when the home itself no longer functions well for the family living in it.
This is especially true when the family has outgrown the house in ways that create daily friction – shared bedrooms, a kitchen that cannot hold everyone at once, no dedicated workspace, a backyard that does not meet what family life actually requires.
The emotional math and the practical math are pulling in different directions. And that tension is exactly where most Whittier move-up buyers are right now.
But Waiting Has Its Own Risks
This is the part many buyers overlook when they decide to wait.
Most people assume that lower rates automatically mean a better buying environment. But if rates eventually decline meaningfully, several things may happen simultaneously:
- More buyers re-enter the market
- Competition for well-priced homes increases
- Inventory tightens
- Home prices rise in response to demand
- Multiple offers become more common again on desirable properties in Whittier’s established neighborhoods
Lower rates may improve the monthly payment calculation – but they can also eliminate the negotiating leverage that currently exists in this market. The Whittier buyer who waits for lower rates may find themselves competing against five other buyers for the same property they could have purchased today with room to negotiate on price, credits, and terms.
Waiting does not guarantee an easier experience. It just changes the specific challenge you are navigating.
The Lifestyle Cost of Waiting Is Real
This is something that does not show up in any spreadsheet but matters enormously in practice.
While a Whittier family waits for rates to improve:
- Kids keep growing
- Sports equipment and school supplies keep accumulating
- The shared bedroom that was supposed to be temporary becomes more permanent
- Morning routines in too-small spaces get harder
- Daily friction compounds slowly until the house feels louder and tighter than it should
Most families do not wake up one morning and suddenly realize they need to move. The feeling builds gradually through months or years of daily stress that wears everyone down before it is consciously recognized as a housing problem.
The cost of staying in a home that no longer fits your family is real – it just does not show up on a mortgage statement.
Interest Rates Matter – But So Does Quality of Life
Sometimes buyers become so focused on optimizing the rate that they stop evaluating how their current home is actually affecting daily life.
Most Whittier move-up buyers are not searching for luxury. They are searching for better flow, more functionality, enough bedrooms that the family does not have to negotiate every morning, and a backyard that actually gets used. Those improvements can change how every single day feels – the stress level walking out the door in the morning, the ability to decompress at home in the evening, the ease of weekend life when everyone has appropriate space.
Waiting years for a perfect rate means years of living with conditions that have already been identified as not working.
Nobody Can Predict the Perfect Time
This is worth saying directly.
No one knows exactly what rates will do, what home prices will do, or what inventory will look like six months or two years from now. Trying to perfectly time all three simultaneously is extremely difficult – and the families who spend years attempting it sometimes look back and realize they waited through conditions that were actually quite workable, in search of conditions that never fully materialized.
The Refinance Option
Many Whittier buyers who are purchasing now are making the decision with the explicit understanding that they can refinance if rates improve meaningfully. This is sometimes described as “date the rate, marry the house” – meaning the rate can be changed later, but the right house in the right neighborhood for your family is a harder thing to replicate once it is gone.
Refinancing is not guaranteed and depends on future rates, your equity position, and your financial qualifications at that time. But for buyers who find a home that genuinely fits their family’s needs and expect to stay for five to ten years or more, the possibility of future refinancing changes the calculus meaningfully.
What Whittier Families Should Actually Be Asking Right Now
Instead of asking only “where will rates go?” – the more useful question is: does our current Whittier home still genuinely support the life we are trying to build?
Because the answer to that question matters just as much as the rate environment.
If the home still fits well, the payment is comfortable, and the daily friction is low – staying and waiting may make sense. There is no urgency to move when the house is working.
But if the home has clearly stopped fitting – if the daily frustration is real, the space is genuinely inadequate, and the family’s quality of life would improve significantly with a move – then the decision to wait is not neutral. It is a choice to continue living in conditions that are not working, in exchange for the possibility of a better rate at an uncertain future date.
The Honest Framework for Thinking It Through
Before deciding to wait, ask yourself honestly:
Does our current Whittier home still support our family’s routines and daily needs? Or are we staying because the familiarity feels safer than change?
Would a different home meaningfully improve our daily stress levels – not in theory, but in the actual practical ways that show up every morning and every evening?
If rates drop and we buy in two years, what will we have given up in quality of life during that period? And is that trade-off worth the potential payment improvement?
Would waiting realistically solve the problem – or would we be waiting in the same conditions, just two years older with kids who are two years further into stages where space and privacy matter more?
Those questions do not have universal answers. They have answers that are specific to your family, your home, your finances, and your goals.
FAQ
Should I wait for interest rates to drop before buying a bigger home in Whittier?
That depends on your personal finances, your family’s space needs, and how much your current home is affecting daily life. Waiting may reduce rates but can also increase competition and home prices, while the lifestyle cost of staying continues to accumulate.
Will home prices go down if rates stay high in Whittier?
No one can predict this with certainty. Whittier’s limited inventory and consistent buyer demand have historically supported values. Any meaningful price shift would depend on a combination of factors beyond rates alone.
Can buyers refinance later if they buy now?
Possibly, depending on future rates and financial qualifications at that time. Many buyers who purchase now are doing so with the explicit plan to refinance if rates improve.
Is now a bad time to move up to a bigger home in Whittier?
Not necessarily. The right answer depends on whether your current home still works for your family and whether the move-up math is viable with your equity and income. Running the real numbers with a lender – not assuming – is the most useful first step.
Ready to Find Out What the Move-Up Math Actually Looks Like for You?
You do not need to be ready to list tomorrow to have this conversation. A single meeting to look at your current equity, what the next home would cost, and what the monthly payment difference actually is – with your equity applied as a down payment – gives you real information instead of assumptions.
Schedule a time to talk about where you are and what a realistic move-up path looks like for your specific situation.
Edgar Cuevas
Whittier and Surrounding Communities | Broker & Owner
Helping buyers and sellers navigate the housing market in:
Whittier - Norwalk - La Mirada - Santa Fe Springs - Pico Rivera - El Monte - Hacienda Heights - La Puente - Valinda - West Covina
Website: xprtrealestate.com
Say hello on socials: Instagram | Facebook | TikTok
Monthly market updates: YouTube
Edgar Cuevas Team is a licensed Broker in the
state of California and is a leading authority in Whittier, in Los Angeles County, California area real estate.
Our love for the communities we live and work in are why we do what we do
© 2026 XprtRealEstate.com. All Rights Reserved.
Meet The Team
Blog
Featured Listings
Sell Your Home
Buy A House
Search Homes
Edgar Cuevas Team is a licensed Broker in the state of California and is a leading authority in the Whittier and the Greater Los Angeles Area.
© 2026 XprtRealEstate.com. All Rights Reserved.