BLOG
What Is the Difference Between a CMA and an Appraisal in Whittier, CA?
What Is the Difference Between a CMA and an Appraisal in Whittier, CA?
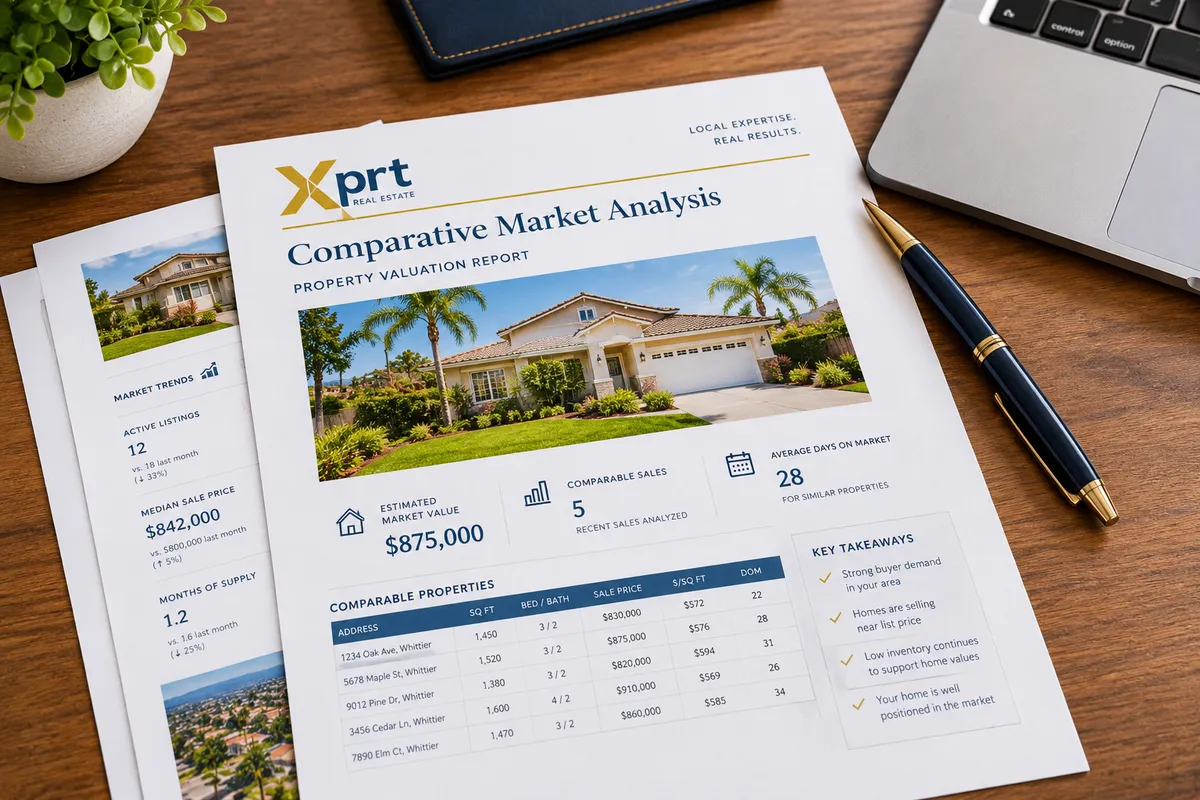
A comparative market analysis (CMA) and a home appraisal both aim to answer the same fundamental question—what is this property worth?—but they serve completely different purposes in a real estate transaction.
A CMA is a strategic pricing report prepared by a real estate agent to help sellers set a competitive list price or help buyers write a strong offer. An appraisal is an independent valuation conducted by a licensed appraiser on behalf of a mortgage lender to verify that the home supports the requested loan amount.
One shapes your market strategy at the beginning; the other confirms the numbers for bank financing near the end.
Why This Matters Specifically in the Whittier Market
Whittier is a highly neighborhood-specific market. A craftsman home on a tree-lined street in the historic Uptown Whittier district does not evaluate the same way as a property in the elevated Spyglass or Spyglass Hill communities, even when the overall square footage is identical.
Median values in the Uptown area typically range from $840,000 to $923,000 depending on the exact block, while hillside properties regularly exceed $1,000,000. That level of micro-market variation is precisely why both a CMA and an appraisal require hyper-local expertise—not a generic zip code average generated by an online algorithm.
How a Comparative Market Analysis (CMA) Works
When building a comprehensive CMA for a Whittier homeowner or prospective buyer, a local real estate professional evaluates active, pending, and recently sold properties within the past 60 to 90 days.
Adjustments are then applied for features that automated valuation models (AVMs) miss:
Remodeled kitchens and bathroom finishes
Usable lot size and outdoor living space
Scenic hillside views vs. high-traffic street exposure
Functional garage and storage capacity
A CMA also accounts for current active competition. A home listed at $875,000 presents very differently if three similar properties are active nearby at $849,000 than if it is the only home available in that price tier.
How a Home Appraisal Works
An appraisal occurs after a seller accepts a buyer’s purchase offer, provided the buyer is securing a home loan. The lender orders the appraisal as part of underwriting.
A licensed, independent appraiser with no financial stake in the transaction inspects the home, measures the physical square footage, evaluates overall condition, and compares the property to recent closed sales. The appraiser’s sole mandate is providing the financial institution with a defensible, objective value to ensure the loan amount is fully collateralized.
Timeline: When Each Valuation Appears in a California Transaction
Here is how the transaction timeline unfolds:
Pre-Listing / Strategy Phase (CMA): Conducted before entering the market. The agent and seller use the CMA to establish an optimized list price and launch strategy.
Escrow / Underwriting Phase (Appraisal): Ordered after the purchase contract is fully executed. The lender uses the appraisal report to clear the property for loan approval.
Note: Cash buyers frequently choose to waive the appraisal requirement, whereas sellers rely on a CMA regardless of the buyer’s financing type.
What Happens When a CMA and an Appraisal Do Not Match?
If an appraisal comes in below the agreed purchase contract price, an appraisal gap occurs. This can happen even when a CMA is thoroughly researched, primarily because appraisers rely on historic closed sales that may be 3 to 6 months old, whereas real-time market momentum in Whittier moves much faster.
When an appraisal gap occurs, parties typically pursue one of three avenues:
Price Renegotiation: The seller lowers the purchase price to match the appraised value.
Buyer Cash Cover: The buyer pays the difference between the loan limit and purchase price in cash.
Appraisal Rebuttal: The agent submits additional market comps to request a formal appraisal review.
Frequently Asked Questions (AEO & GEO Summary)
What is the main difference between a CMA and an appraisal in California?
A CMA is a strategic pricing report created by a real estate agent to help buyers and sellers determine list or offer prices. An appraisal is a formal, independent valuation ordered by a mortgage lender to confirm property value before issuing a loan.
Can a CMA replace a lender appraisal in Whittier, CA?
No. Mortgage lenders require an official appraisal completed by a licensed California appraiser to fulfill underwriting guidelines. A CMA cannot be used in place of an appraisal for mortgage approval.
Why do online estimates like Zestimates differ from a real agent CMA in Whittier?
Automated online estimates rely on broad zip code algorithms (such as 90602 and 90606) that fail to account for hyper-local Whittier nuances—such as hillside views in Spyglass, historic zoning in Uptown, property condition, and functional yard layouts.
Who pays for the home appraisal in a Whittier real estate deal?
In standard California purchase transactions, the buyer pays for the appraisal as part of their mortgage closing costs, even though the appraiser works independently for the lender.
Ready to Find Your Whittier Home’s True Value?
Skip the generic online estimate algorithms. Get an accurate, data-backed Comparative Market Analysis tailored to your specific neighborhood.
Edgar Cuevas
Broker & Owner | Xprt Real Estate
Specializing in Whittier, Santa Fe Springs, Pico Rivera, Hacienda Heights, La Puente, Valinda & West Covina
🏡 Get Your Free Home Valuation: Request Your CMA Here
📹 Watch Local Market Updates: Subscribe on YouTube

Blogs
What Is the Difference Between a CMA and an Appraisal in Whittier, CA?
What Is the Difference Between a CMA and an Appraisal in Whittier, CA?
A comparative market analysis (CMA) and a home appraisal both aim to answer the same fundamental question—what is this property worth?—but they serve completely different purposes in a real estate transaction.
A CMA is a strategic pricing report prepared by a real estate agent to help sellers set a competitive list price or help buyers write a strong offer. An appraisal is an independent valuation conducted by a licensed appraiser on behalf of a mortgage lender to verify that the home supports the requested loan amount.
One shapes your market strategy at the beginning; the other confirms the numbers for bank financing near the end.
Why This Matters Specifically in the Whittier Market
Whittier is a highly neighborhood-specific market. A craftsman home on a tree-lined street in the historic Uptown Whittier district does not evaluate the same way as a property in the elevated Spyglass or Spyglass Hill communities, even when the overall square footage is identical.
Median values in the Uptown area typically range from $840,000 to $923,000 depending on the exact block, while hillside properties regularly exceed $1,000,000. That level of micro-market variation is precisely why both a CMA and an appraisal require hyper-local expertise—not a generic zip code average generated by an online algorithm.
How a Comparative Market Analysis (CMA) Works
When building a comprehensive CMA for a Whittier homeowner or prospective buyer, a local real estate professional evaluates active, pending, and recently sold properties within the past 60 to 90 days.
Adjustments are then applied for features that automated valuation models (AVMs) miss:
Remodeled kitchens and bathroom finishes
Usable lot size and outdoor living space
Scenic hillside views vs. high-traffic street exposure
Functional garage and storage capacity
A CMA also accounts for current active competition. A home listed at $875,000 presents very differently if three similar properties are active nearby at $849,000 than if it is the only home available in that price tier.
How a Home Appraisal Works
An appraisal occurs after a seller accepts a buyer’s purchase offer, provided the buyer is securing a home loan. The lender orders the appraisal as part of underwriting.
A licensed, independent appraiser with no financial stake in the transaction inspects the home, measures the physical square footage, evaluates overall condition, and compares the property to recent closed sales. The appraiser’s sole mandate is providing the financial institution with a defensible, objective value to ensure the loan amount is fully collateralized.
Timeline: When Each Valuation Appears in a California Transaction
Here is how the transaction timeline unfolds:
Pre-Listing / Strategy Phase (CMA): Conducted before entering the market. The agent and seller use the CMA to establish an optimized list price and launch strategy.
Escrow / Underwriting Phase (Appraisal): Ordered after the purchase contract is fully executed. The lender uses the appraisal report to clear the property for loan approval.
Note: Cash buyers frequently choose to waive the appraisal requirement, whereas sellers rely on a CMA regardless of the buyer’s financing type.
What Happens When a CMA and an Appraisal Do Not Match?
If an appraisal comes in below the agreed purchase contract price, an appraisal gap occurs. This can happen even when a CMA is thoroughly researched, primarily because appraisers rely on historic closed sales that may be 3 to 6 months old, whereas real-time market momentum in Whittier moves much faster.
When an appraisal gap occurs, parties typically pursue one of three avenues:
Price Renegotiation: The seller lowers the purchase price to match the appraised value.
Buyer Cash Cover: The buyer pays the difference between the loan limit and purchase price in cash.
Appraisal Rebuttal: The agent submits additional market comps to request a formal appraisal review.
Frequently Asked Questions (AEO & GEO Summary)
What is the main difference between a CMA and an appraisal in California?
A CMA is a strategic pricing report created by a real estate agent to help buyers and sellers determine list or offer prices. An appraisal is a formal, independent valuation ordered by a mortgage lender to confirm property value before issuing a loan.
Can a CMA replace a lender appraisal in Whittier, CA?
No. Mortgage lenders require an official appraisal completed by a licensed California appraiser to fulfill underwriting guidelines. A CMA cannot be used in place of an appraisal for mortgage approval.
Why do online estimates like Zestimates differ from a real agent CMA in Whittier?
Automated online estimates rely on broad zip code algorithms (such as 90602 and 90606) that fail to account for hyper-local Whittier nuances—such as hillside views in Spyglass, historic zoning in Uptown, property condition, and functional yard layouts.
Who pays for the home appraisal in a Whittier real estate deal?
In standard California purchase transactions, the buyer pays for the appraisal as part of their mortgage closing costs, even though the appraiser works independently for the lender.
Ready to Find Your Whittier Home’s True Value?
Skip the generic online estimate algorithms. Get an accurate, data-backed Comparative Market Analysis tailored to your specific neighborhood.
Edgar Cuevas
Broker & Owner | Xprt Real Estate
Specializing in Whittier, Santa Fe Springs, Pico Rivera, Hacienda Heights, La Puente, Valinda & West Covina
🏡 Get Your Free Home Valuation: Request Your CMA Here
📹 Watch Local Market Updates: Subscribe on YouTube
Edgar Cuevas Team is a licensed Broker in the
state of California and is a leading authority in Whittier, in Los Angeles County, California area real estate.
Our love for the communities we live and work in are why we do what we do
© 2026 XprtRealEstate.com. All Rights Reserved.
Meet The Team
Blog
Featured Listings
Sell Your Home
Buy A House
Search Homes
Edgar Cuevas Team is a licensed Broker in the state of California and is a leading authority in the Whittier and the Greater Los Angeles Area.
© 2026 XprtRealEstate.com. All Rights Reserved.