BLOG
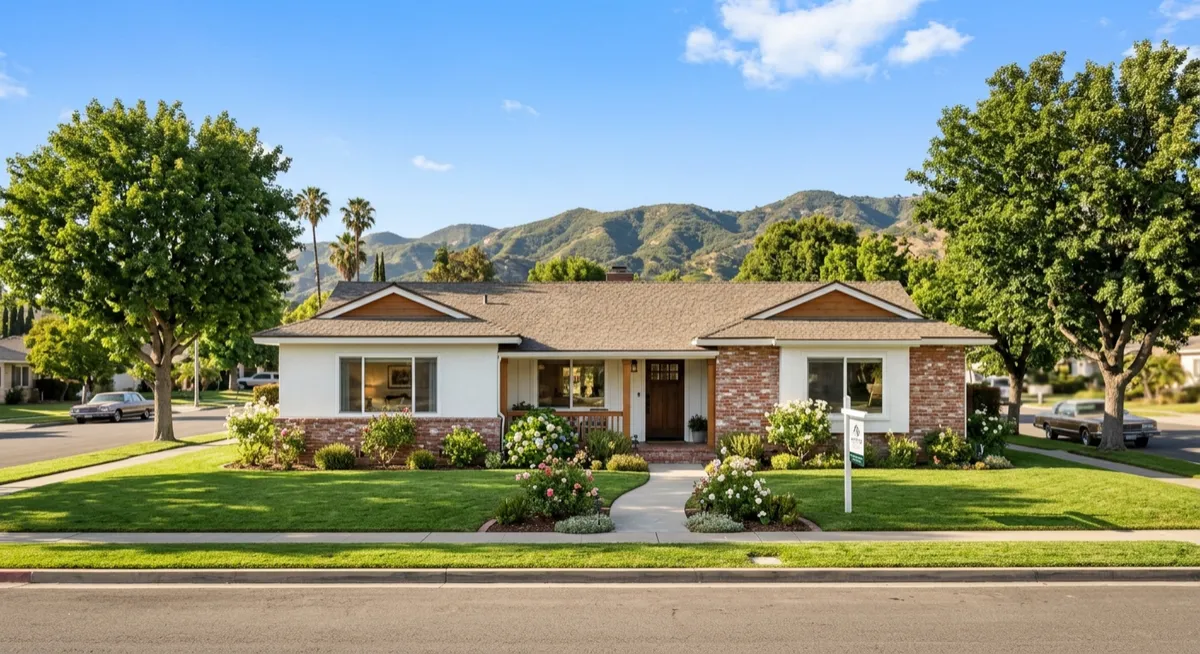
What You Should Know Before Buying a Foreclosure or Bank-Owned Home in Whittier, CA
What You Should Know Before Buying a Foreclosure or Bank-Owned Home in Whittier, CA
Distressed properties and bank-owned homes frequently catch the attention of Whittier home buyers seeking investment value or discounts off market prices.
While buying a foreclosure can offer real financial upside, purchasing bank-owned real estate in Los Angeles County involves unique contract terms, strict “as-is” clauses, and title considerations.
Here is what every buyer should know before submitting an offer on a foreclosure or bank-owned property in Whittier, California.
Understanding REO vs. Short Sale Properties in Whittier
Property Type | Ownership Status | Purchase Timeline | Key Transaction Characteristic |
|---|---|---|---|
REO (Real Estate Owned) | Bank / Lender owns title after auction | Standard 30–45 days | Sold “as-is” directly by bank asset manager |
Short Sale | Distressed homeowner still owns title | Extended (60–120+ days) | Requires lender approval of price below debt |
Auction / Trustee Sale | Foreclosure auction at courthouse | Immediate cash closing | High risk; no interior access or standard inspection |
This guide focuses primarily on REO (Real Estate Owned) bank-owned properties listed on the Whittier MLS.
5 Crucial Factors When Buying a Bank-Owned REO Home
1. Strict “As-Is” Purchase Terms
Banks will not repair defects, offer seller repair credits, or negotiate on cosmetic updates. The price reflects current physical condition.
2. Utility Deactivation & Inspection Challenges
Vacant bank homes often have water, gas, and power shut off. Buyers must coordinate with asset managers to activate utilities temporarily for home, sewer scope, and pest inspections.
3. Lengthy Vacancy Deterioration
Properties sitting vacant in Whittier neighborhoods like Uptown, Friendly Hills, or Murphy Ranch can develop plumbing leaks, roof issues, or deferred maintenance that requires dedicated repair reserves.
4. Special Bank Contract Addendums
Bank asset managers require buyers to sign custom REO addendums that override standard California Association of REALTORS® (C.A.R.) purchase contract terms regarding per-diem penalties and inspection timelines.
5. Title & Lien Clearance Requirements
Ensure your title company conducts a comprehensive title search to clear historical tax liens, mechanic’s liens, or unpaid municipal code enforcement violations before closing.
Frequently Asked Questions
Are bank-owned REO homes cheaper in Whittier, CA?
REO properties are often listed slightly below market value to reflect deferred maintenance. However, buyers must factor in required renovation costs to determine true net value.
Can you negotiate on a bank-owned home purchase in California?
Yes. Bank asset managers evaluate offers based on recent neighborhood comparable sales, net proceeds, and buyer financing strength (such as strong pre-approval or cash verification).
What is the biggest risk when buying a foreclosure in Los Angeles County?
The largest risk is waiving physical inspections or purchasing without clear title insurance, which can expose buyers to unrecorded liens or severe structural defects.
Searching for Buyer Value in Whittier Real Estate?
Whether you are evaluating bank-owned inventory or standard residential listings, let’s navigate the local market together.
Edgar Cuevas
Broker & Owner | Xprt Real Estate
Specializing in Whittier, Norwalk, La Mirada, Santa Fe Springs, Pico Rivera, El Monte, Hacienda Heights, La Puente, Valinda & West Covina
📅 Schedule a Buyer Consultation: Book a Strategy Call
📹 Watch Local Market Updates: Subscribe on YouTube

Blogs
What You Should Know Before Buying a Foreclosure or Bank-Owned Home in Whittier, CA
What You Should Know Before Buying a Foreclosure or Bank-Owned Home in Whittier, CA
Distressed properties and bank-owned homes frequently catch the attention of Whittier home buyers seeking investment value or discounts off market prices.
While buying a foreclosure can offer real financial upside, purchasing bank-owned real estate in Los Angeles County involves unique contract terms, strict “as-is” clauses, and title considerations.
Here is what every buyer should know before submitting an offer on a foreclosure or bank-owned property in Whittier, California.
Understanding REO vs. Short Sale Properties in Whittier
Property Type | Ownership Status | Purchase Timeline | Key Transaction Characteristic |
|---|---|---|---|
REO (Real Estate Owned) | Bank / Lender owns title after auction | Standard 30–45 days | Sold “as-is” directly by bank asset manager |
Short Sale | Distressed homeowner still owns title | Extended (60–120+ days) | Requires lender approval of price below debt |
Auction / Trustee Sale | Foreclosure auction at courthouse | Immediate cash closing | High risk; no interior access or standard inspection |
This guide focuses primarily on REO (Real Estate Owned) bank-owned properties listed on the Whittier MLS.
5 Crucial Factors When Buying a Bank-Owned REO Home
1. Strict “As-Is” Purchase Terms
Banks will not repair defects, offer seller repair credits, or negotiate on cosmetic updates. The price reflects current physical condition.
2. Utility Deactivation & Inspection Challenges
Vacant bank homes often have water, gas, and power shut off. Buyers must coordinate with asset managers to activate utilities temporarily for home, sewer scope, and pest inspections.
3. Lengthy Vacancy Deterioration
Properties sitting vacant in Whittier neighborhoods like Uptown, Friendly Hills, or Murphy Ranch can develop plumbing leaks, roof issues, or deferred maintenance that requires dedicated repair reserves.
4. Special Bank Contract Addendums
Bank asset managers require buyers to sign custom REO addendums that override standard California Association of REALTORS® (C.A.R.) purchase contract terms regarding per-diem penalties and inspection timelines.
5. Title & Lien Clearance Requirements
Ensure your title company conducts a comprehensive title search to clear historical tax liens, mechanic’s liens, or unpaid municipal code enforcement violations before closing.
Frequently Asked Questions
Are bank-owned REO homes cheaper in Whittier, CA?
REO properties are often listed slightly below market value to reflect deferred maintenance. However, buyers must factor in required renovation costs to determine true net value.
Can you negotiate on a bank-owned home purchase in California?
Yes. Bank asset managers evaluate offers based on recent neighborhood comparable sales, net proceeds, and buyer financing strength (such as strong pre-approval or cash verification).
What is the biggest risk when buying a foreclosure in Los Angeles County?
The largest risk is waiving physical inspections or purchasing without clear title insurance, which can expose buyers to unrecorded liens or severe structural defects.
Searching for Buyer Value in Whittier Real Estate?
Whether you are evaluating bank-owned inventory or standard residential listings, let’s navigate the local market together.
Edgar Cuevas
Broker & Owner | Xprt Real Estate
Specializing in Whittier, Norwalk, La Mirada, Santa Fe Springs, Pico Rivera, El Monte, Hacienda Heights, La Puente, Valinda & West Covina
📅 Schedule a Buyer Consultation: Book a Strategy Call
📹 Watch Local Market Updates: Subscribe on YouTube
Edgar Cuevas Team is a licensed Broker in the
state of California and is a leading authority in Whittier, in Los Angeles County, California area real estate.
Our love for the communities we live and work in are why we do what we do
© 2026 XprtRealEstate.com. All Rights Reserved.
Meet The Team
Blog
Featured Listings
Sell Your Home
Buy A House
Search Homes
Edgar Cuevas Team is a licensed Broker in the state of California and is a leading authority in the Whittier and the Greater Los Angeles Area.
© 2026 XprtRealEstate.com. All Rights Reserved.